Heat pump leasing: when does it beat buying
Last edited
Author
Andrew Blok
Electrification and Solar Writer and Editor
Editor
Andrew Giermak
Solar and Electrification Writer and Editor
If your furnace or AC is on its last legs, your replacement quote could reach $30,000 depending on your home’s heating and cooling needs.
Maybe you’ve heard of $0 down HVAC leasing, but feel skeptical. That’s fair, though leasing is the right choice for some homes. Here’s how it works.
How does a heat pump lease work?
With a heat pump lease, you pay $0 upfront. Instead, you make fixed monthly payments, and the company that owns the system covers service and repairs for the full 10-year term. Palmetto Comfort Plan works this way.
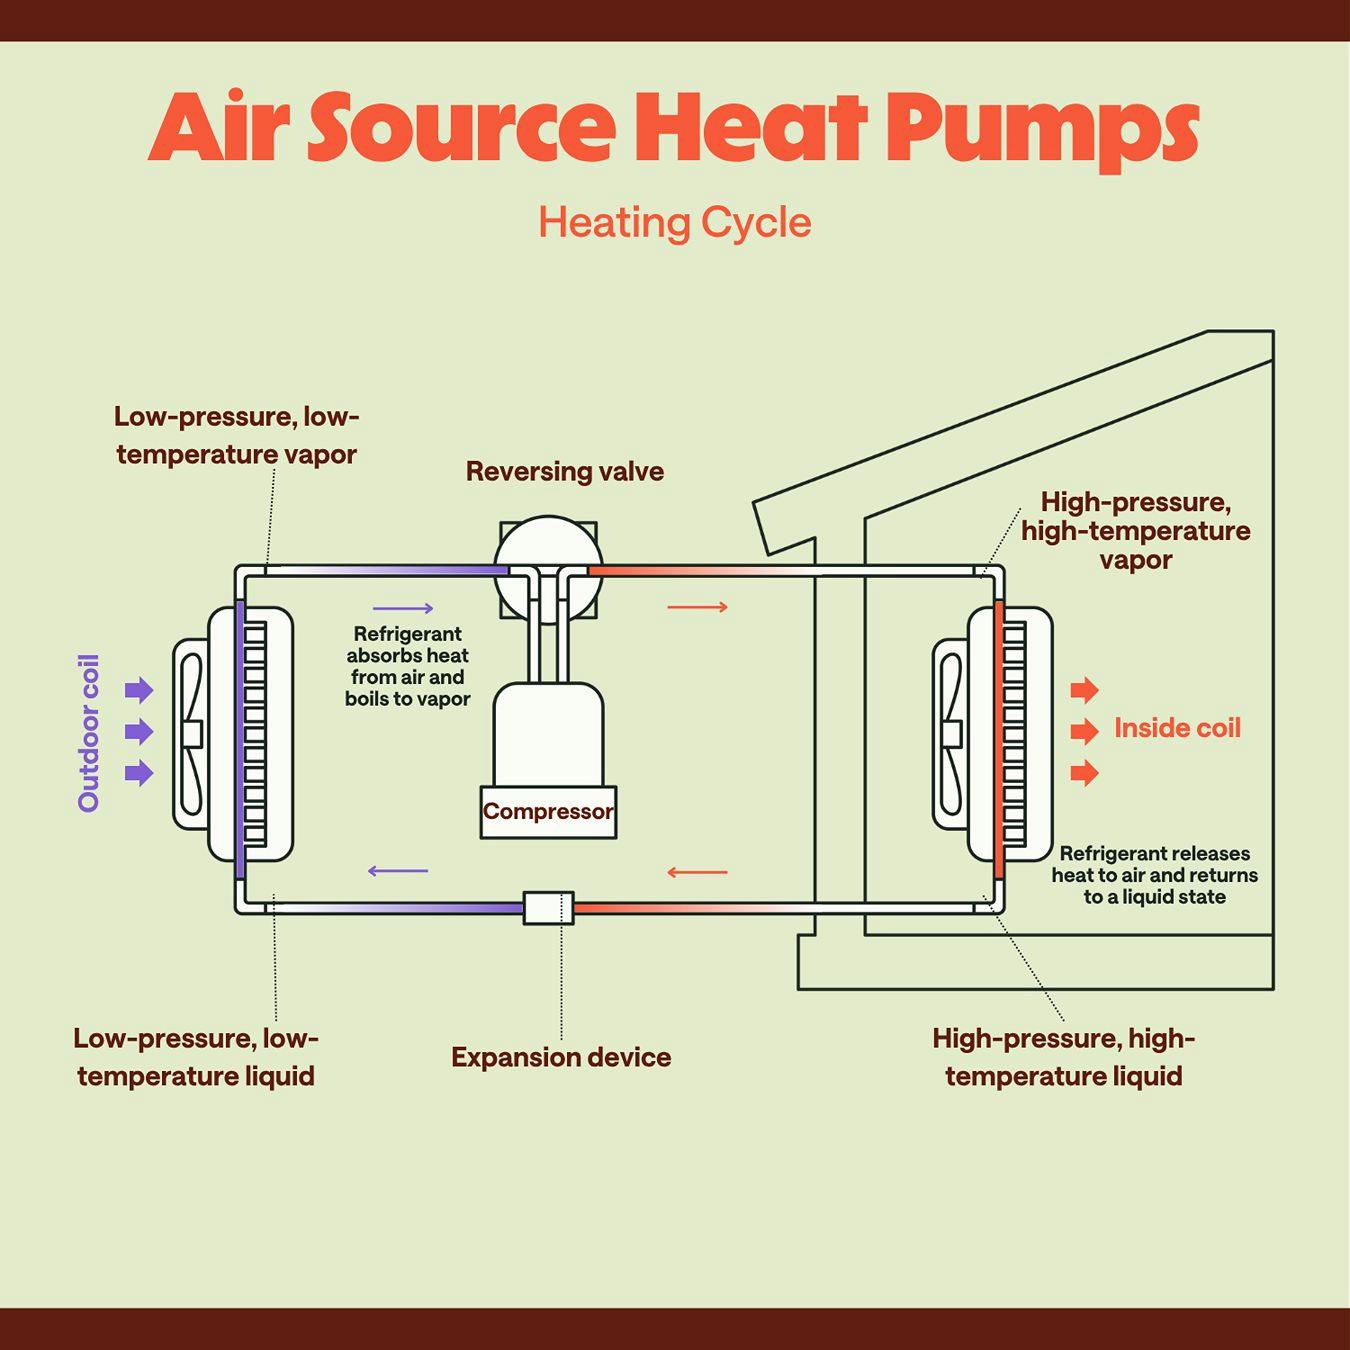
A heat pump both heats and cools your home, moving heat instead of generating it, so it uses less electricity than an electric furnace or electric baseboard heaters. According to the Department of Energy, they can use just 50% the electricity of electric baseboard heaters and furnaces.
A lease fits best if you want no upfront cost and no repair risk. It fits less well if you have the cash and don’t mind coordinating and paying for maintenance and repair.
What do you actually pay for each month?
Monthly lease payments typically cover the same things, though the amount will vary by system size and type. Payments cover the system, installation, maintenance, service, and repairs. Palmetto's partners assess your home and handle the install.
Two things to ask any lease company, including us:
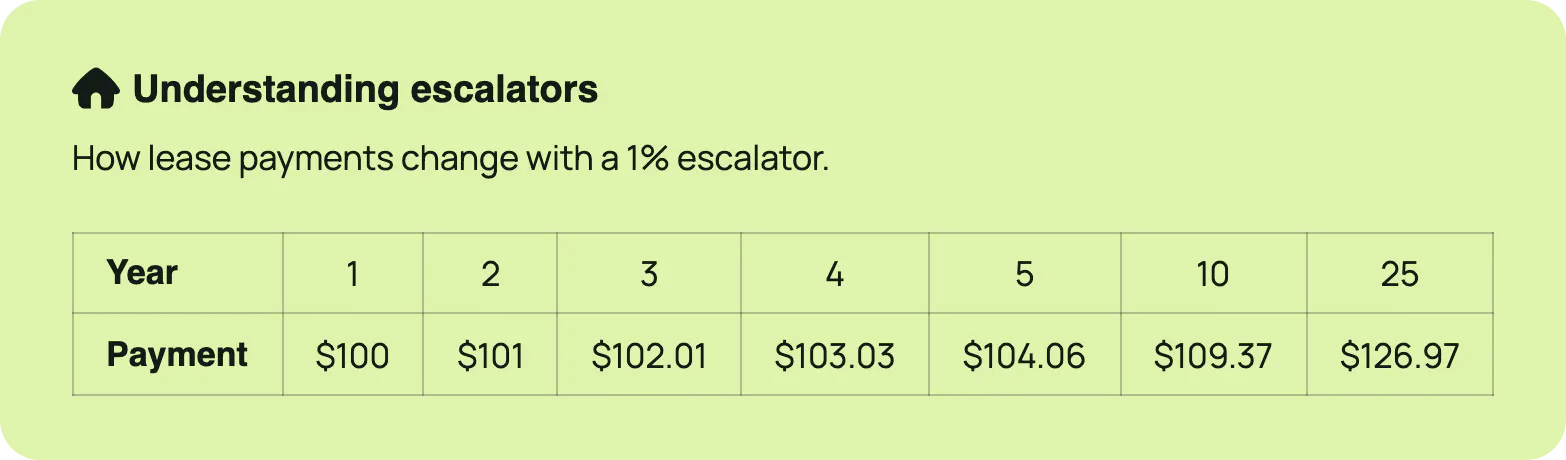
- Does the payment go up over time? Some leases come with a lease escalator (often .99% or 1.99%). Escalators raise your lease payment by that set amount each year, meaning your costs increase incrementally over time.
- Are there extra costs at install? Older homes sometimes need duct or electrical work first. Those costs can be rolled into the lease payment and spread out over the lease term.
Will a lease lower your total costs?
You'll have two monthly costs: the lease payment and your electric bill. A heat pump lease’s cost benefit is in avoiding the upfront cost and spreading it across monthly payments, but it’s not necessarily going to deliver you lower overall costs for your HVAC system.
Heat pumps can reduce your energy costs, especially if you're replacing heating oil, propane, or electric resistance heat. Those are expensive ways to heat a home, and a heat pump often beats them by a wide margin. If you're replacing a newer gas furnace in a state with cheap natural gas, your energy bill may not drop much or even go up. A 2024 DOE study found 90% of American households could lower their energy bills with the right heat pump, regardless of what fuel you switch from.
What's covered, and what isn't?
Maintenance, service, and repairs are typically included. Intentional damage or damage from neglect won’t be.
Read the service terms in any lease before you sign. A service agreement you accidentally break can cost you.
Should you lease or buy?
Lease if you don't want to pay the entire cost upfront, you want a predictable monthly cost, and you'd rather not worry about a repair bill in year seven.
Buy if you have the cash and you want to own the system outright. Over the full term, you may pay more in total with a lease than with a purchase.
State and utility rebates for heat pumps do exist, and some can be claimed when the heat pump is leased. Some go to the homeowners, while others go to the contractor that installs the heat pump. In some cases, they might be used to reduce your lease payment, but rebates that go directly to you are likely to be paid as a lump sum after installation. Be sure you understand the specifics of any incentives available to you before counting on them.
One real tradeoff is a long contract. It’ll last at least 10 years, and leaving early will require you to buy out the rest of your lease.
| Leasing | Purchase (no loan) | Loan purchase | |
|---|---|---|---|
| Initial cost | None | Full equipment and installation cost | Down payment |
| Monthly cost | Lease payment + electric bill | Electric bill | Loan payment + electric bill |
| Interest | No | No | Yes |
| Maintenance | Included | Your responsibility | Your responsibility |
| Tax credits/incentives (where available) | Owned and managed by leasing company | Potentially eligible | Potentially eligible |
What happens at the end of the lease, or if you sell your home?
At the end of the 10-year term, you have three choices: renew at a reduced monthly rate, buy the system at its current value, or upgrade to a newer model.
If you sell your home before the term ends, you can transfer the lease to the new homeowner, buy it out at closing, or prepay the lease for the new homeowner. Ask about this upfront with any lease.
If you want to know what a lease would cost for your home, Palmetto's HVAC advisor can give you a real estimate in a few minutes.
See how much you can save with a new HVAC system from Palmetto
Frequently asked questions
Will leasing a heat pump save me money?
Leasing a new energy-efficient heat pump can reduce your energy bills compared to your old HVAC system. Whether you’ll save or how much will depend on the system you’re replacing, your lease payments, your local energy prices, and your eligibility for incentives.
What are the benefits of a heat pump lease?
A heat pump lease’s main benefit is shifting the large upfront cost of purchase and installation to predictable monthly payments. Those payments also cover maintenance and most repairs, and get you access to flexible end-of-term options after the 10-year term is up.
What are the downsides of a heat pump lease?
Heat pump leases are predictable and remove some of the responsibilities of ownership, but give up some of the flexibility, too. You’ll need to buy out your lease to end it early. If you sell your home, you’ll need to transfer or buy out your lease at that point, too. In some cases, the total cost of a heat pump lease may be higher than a cash purchase.
Disclaimer: This content is for educational purposes only. Palmetto does not provide tax, legal, or accounting advice. Please consult your own tax, legal, and accounting advisors.


